New - 30 Mins Ago
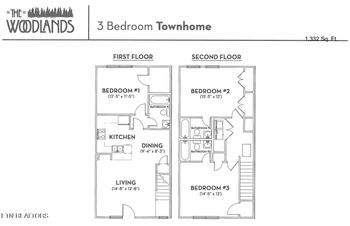
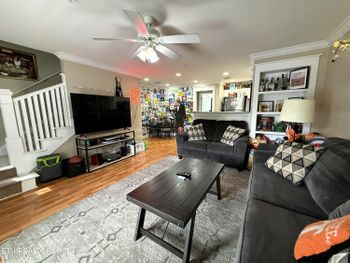
$357,000
Active
3
Beds
3
Baths
1332
Sqft
0.01
Acres
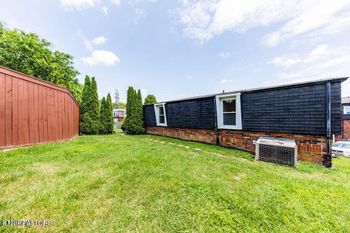
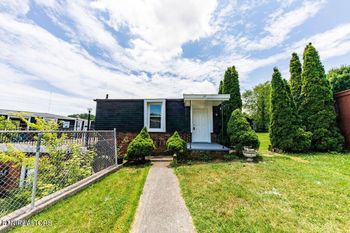
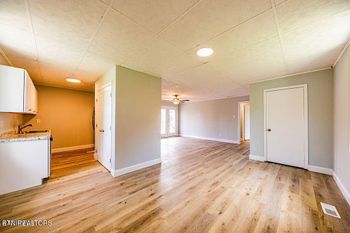
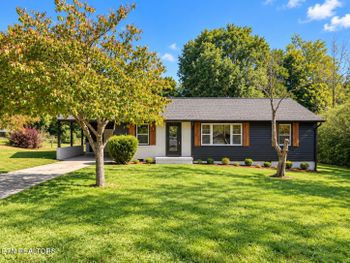
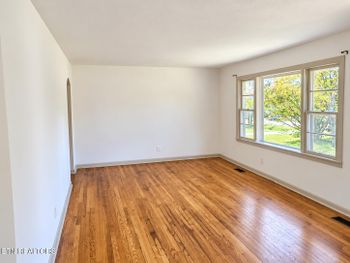
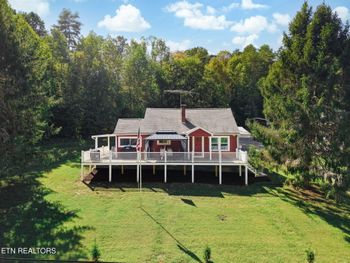
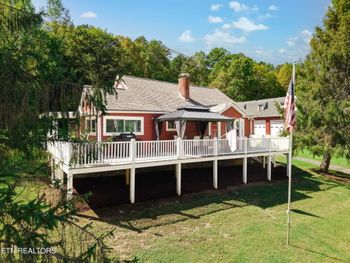
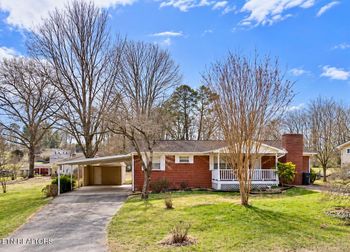
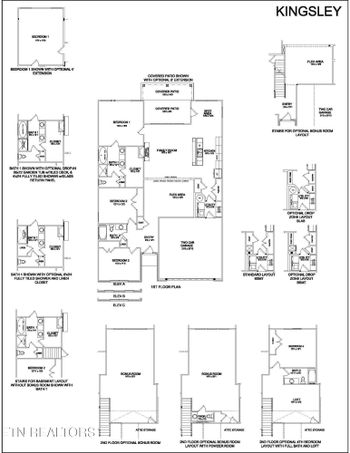
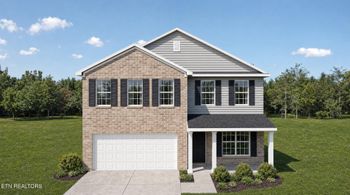
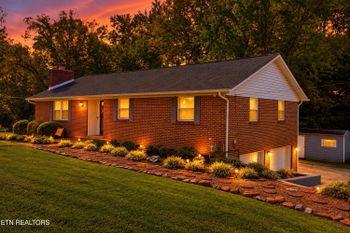
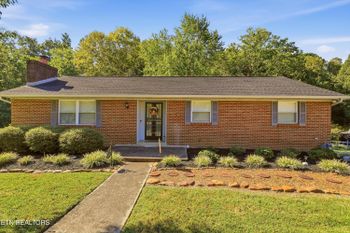
1105 Tree Top Way #1726, Knoxville, TN 37920
MLS#: 1358569


Your first Knoxville home needs to work on an ordinary Tuesday as well as it does at the showing. Start with a monthly payment you can live with, a commute you have tried, and enough money left after closing to handle the house itself.
These steps take you from the first lender conversation to getting the keys. If you are also choosing where to live, use our Moving to Knoxville guide alongside this one.
A lender's approval amount is a starting point. Decide what payment leaves room for your other expenses and savings before you tour homes. Then work out how much cash you can put into the purchase without emptying your reserves.
Ask your lender which costs are included in its cash-to-close estimate and which you will pay separately. That helps prevent both missing a cost and counting it twice. The CFPB's Loan Estimate explainer walks through the payment, fees, and cash-to-close figures.
If your lease ends on a fixed date, check the notice deadline and whether an extension is available before building your purchase schedule around it. Price a backup housing option in case your purchase does not close on the date you expect.
Talk with lenders about preapproval, the documents they need, and any conditions that remain. Ask how a change in price, down payment, or interest rate would affect your payment. Before changing jobs, opening credit, or moving large sums during the purchase, ask your lender how that could affect your application.
When you receive loan offers, compare the same loan type, term, and rate-lock assumptions. A lower quoted payment may reflect a different tax or insurance estimate rather than a cheaper loan. The CFPB explains how to compare Loan Estimates.
Ask about Tennessee assistance early. THDA offers homebuyer programs, including Great Choice. Its Great Choice Plus assistance is a second loan for eligible borrowers, not simply cash with no conditions. Check the current THDA requirements and ask your lender to explain eligibility, any applicable education requirements, repayment terms, and the total cost with and without assistance. Do this before you make an offer that depends on the program.
Write down your work address, regular appointments, and the places you visit most. A home near downtown Knoxville and one near Farragut may both appear in a broad Knoxville search, but they need separate commute tests. Drive from the actual house at the time you would normally leave, then try the return trip.
Choose three must-haves and three things you can compromise on. If widening the search gives you more workable home options, decide how much additional weekday driving you would actually accept before expanding the map. For example, a usable home office and a manageable drive may matter more than a newly remodeled kitchen. Check parking, steps, storage, and the yard in person. If school assignment matters to your move, use the KGIS Maps school-zone information and confirm the address and school year with the district.
Two homes at the same asking price can cost different amounts to own. Before you choose a home, collect the tax records, an insurance quote, HOA documents if applicable, and utility information for each address.
The City of Knoxville maintains a city property-tax search separate from the Knox County tax search. Check which bills apply; do not use the mailing address alone to decide. Ask your lender how it has estimated taxes for your purchase, especially for new construction.
Also confirm who provides fire protection and whether you need to arrange a separate membership. Our Rural Metro guide explains the address checks. For an HOA or condo association, read the fees, maintenance responsibilities, restrictions, and any disclosed assessments before deciding that a lower purchase price is the better deal.
Before you hire an inspector, ask what the standard inspection covers, what it does not cover, and when the inspector may recommend evaluation by a specialist. A fresh kitchen does not tell you the condition of the roof, wiring, heating system, or crawl space. Ask the inspector about moisture, drainage, visible repairs, and anything that needs a specialist's opinion. If the property has a well or septic system, ask what separate evaluation is appropriate. If significant work is identified, get estimates while you still have time to evaluate your options under the contract.
An appraisal estimates value for the lending process; it does not replace your home inspection. The CFPB's inspection guidance explains the difference and why scheduling promptly matters.
Discuss insurance for the address before the purchase is too far along. Use FEMA's Flood Map Service Center as one starting point, and ask your insurer about flood coverage and other relevant exclusions. A map does not replace a property inspection or an insurance conversation.
Ask your agent to compare the home with relevant recent sales, taking condition and location into account. Then review the entire offer: earnest money, financing, inspection and appraisal terms, requested seller contributions, closing date, and possession.
Before signing, be able to answer three questions: What do I owe next? What must happen by each deadline? What happens if a condition is not met? Have your agent explain the transaction terms and bring legal questions to an attorney. Do not assume a deposit is refundable or that you can cancel simply because you change your mind.
If an appraisal comes in below the contract price, the options depend on your financing and contract. Discuss that possibility before agreeing to cover a gap with additional cash.
For most purchase mortgages, you must receive a Closing Disclosure at least three business days before closing. Use that time to compare the final loan terms and cash needed with your earlier estimate, and ask about differences. See the CFPB's Closing Disclosure timing guidance.
Arrange a final walk-through to check the agreed condition, included items, and any agreed repairs. Confirm the possession time before booking movers. Set up utilities and insurance for the appropriate dates, and keep repair records, warranties, and service contacts together.
Keep the first week's spending modest until you know what the house needs. Furniture can wait longer than a repair that affects your ability to use the home.
Whether you are still saving, talking with lenders, or ready to tour, share your timing and what you need from your first home. The Knox Fox team can help you turn those priorities into a focused Knoxville search.